Guides
CFPB Complaint Data Reveals Finance App Patterns Before You Sign Up
CFPB complaint data on finance apps shows volume, response and resolution before you sign up. Here is what to measure, what it misses, and when to walk away.
What to take away
- The CFPB Consumer Complaint Database is a free, searchable record of complaints routed to companies, and it shows volume, product, issue and whether the company gave a timely response.
- Complaint share, not raw complaint count, is the number to watch: complaints divided by a rough measure of users or accounts. A rise of 50 percent or more over two consecutive quarters is a reasonable trigger to slow down and read the narratives.
- The database records complaints, not verified wrongdoing. A company with no complaints may simply be small, new, or unlisted.
- Response categories tell you about process. "Closed with explanation" and "Closed with non-monetary relief" mean different things, and neither proves the customer was made whole.
What to measure
The database lets you filter by company, product, issue, state, and date, then by on-time response. Start with the company's legal name, not the app name.
Many finance apps are brands operated by a licensed bank or program manager, so the record may sit under the bank. The CFPB Consumer Complaint Database is the source. The agency's data use notes say complaints publish after the company responds or after 15 days, whichever comes first.
Pull the last eight quarters. Note three figures: total complaints, the share tied to money movement or account access, and the share closed with relief. Then divide complaints by a rough user base if one is public. That gives you a complaint rate you can compare across apps.
| Metric | Definition | Why it matters |
|---|---|---|
| Complaint volume | Count of complaints in the period | Shows scale of friction |
| Complaint rate | Complaints divided by estimated users | Lets you compare a large app with a small one |
| Relief share | Complaints closed with monetary or non-monetary relief | Signals how often the company fixes things |
| Timely response | Share answered within the CFPB window | Signals operational capacity |
How to read it
Read the issue codes before the totals, because complaints clustered around "problem with a purchase shown on your statement" point to disputes. Complaints about "funds not received" or "account closed" point to settlement and access.
For apps holding balances through a partner bank, check the partner's record too, because deposit insurance and error resolution sit with the institution. The FDIC deposit insurance resources explain what pass-through coverage does and does not protect.
Sort by date and look for step changes. A jump that lines up with a product launch, a fee change or a funding round is worth a closer look. Read ten narratives in full. Narratives are optional and unverified, so treat them as leads, not findings.
What it cannot tell you
The database cannot tell you the size of the denominator. Complaints are self-selected, and the CFPB does not publish user counts. A rate built on an estimated user base is a rough ratio, not a measurement, and it can be wrong by a wide margin.
It also cannot tell you whether a complaint is accurate, and companies can dispute facts; the CFPB does not adjudicate. Relief categories are broad: "non-monetary relief" can mean a corrected record or a courtesy response.
The database covers only companies under CFPB supervision or those that respond voluntarily, so a state-licensed money transmitter with a thin federal footprint may have a short record. The money transmitter overview shows how state licensing splits oversight.
Attribution and its limits
A complaint spike is not proof of a design flaw. It can follow a growth spurt, a marketing push, or a change in how a company labels its product in the database. Product labels shift, and companies sometimes reclassify. Compare like periods and like products.
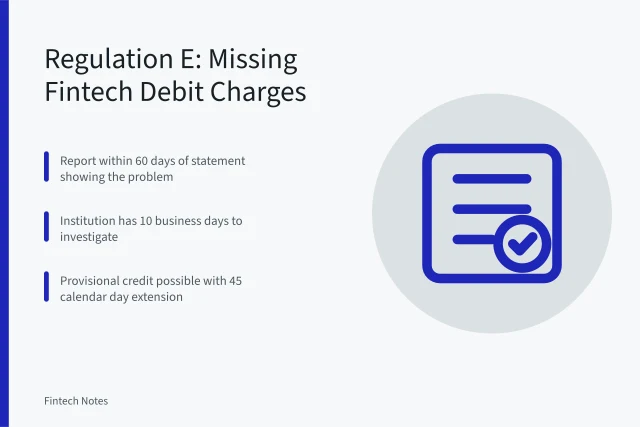
Where an app offers early access to wages, check whether the product is treated as credit. The CFPB paycheck advance rule is the place to start, and the Regulation E text sets the error resolution clock for electronic transfers. If complaints cluster around unauthorized transfers, the 60-day window for reporting is the rule that decides who eats the loss.
A complaint rate is a smoke signal, not a diagnosis. Use it to decide what to read, then read.
When to stop measuring and decide
Set the threshold before you look. If the complaint rate rises 50 percent or more across two quarters while the app is not growing fast, treat that as a stop sign. Check the digital bank and finance app due-diligence checklist before you fund an account.
If relief share falls below a quarter of complaints in the same window, ask the company directly how it resolves disputes.
A thin record is not a pass. Move to the digital payment product evaluation checklist and test the app with a small balance first.
Where you plan a larger balance, the digital account guide explains who holds the money and what insurance applies. If you send money between institutions, the bank transfer guide covers timing and reversal limits.
Stop when you have enough to decide. Two quarters of data, ten narratives, and one direct answer from support is enough for most accounts.